China's GDP growth accelerated to 4.5% in the third quarter of 2026, beating market forecasts as exports and industrial production offset weak consumer demand and a deep property downturn.
The result improved from 4.3% growth in the April-to-June quarter and topped the 4.4% median forecast in a Reuters poll. On a seasonally adjusted basis, output rose 1.2% from the previous quarter, according to China's National Bureau of Statistics.
China GDP Growth Beats Forecasts at 4.5%
China's economy generated 107.11 trillion yuan in the first nine months of 2026, up 4.6% from a year earlier. The quarterly path shows a sharp contrast: growth ran at 5.0% in the first quarter, slowed to 4.3% in the second and recovered to 4.5% in the third.
The headline figures were stronger than expected:
- Q3 GDP: up 4.5% year on year, versus a 4.4% forecast.
- Quarter-on-quarter GDP: up 1.2%, versus a 1.1% forecast.
- September industrial output: up 5.5% year on year.
- September retail sales: up 1.1%, ahead of the 0.6% forecast.
The rebound keeps Beijing's full-year growth target of 4.5% to 5% within reach. China's government portal said the economy added 5.7 trillion yuan in output during the period, the largest increase for the same nine-month window in five years.
Exports and High-Tech Manufacturing Drive Growth
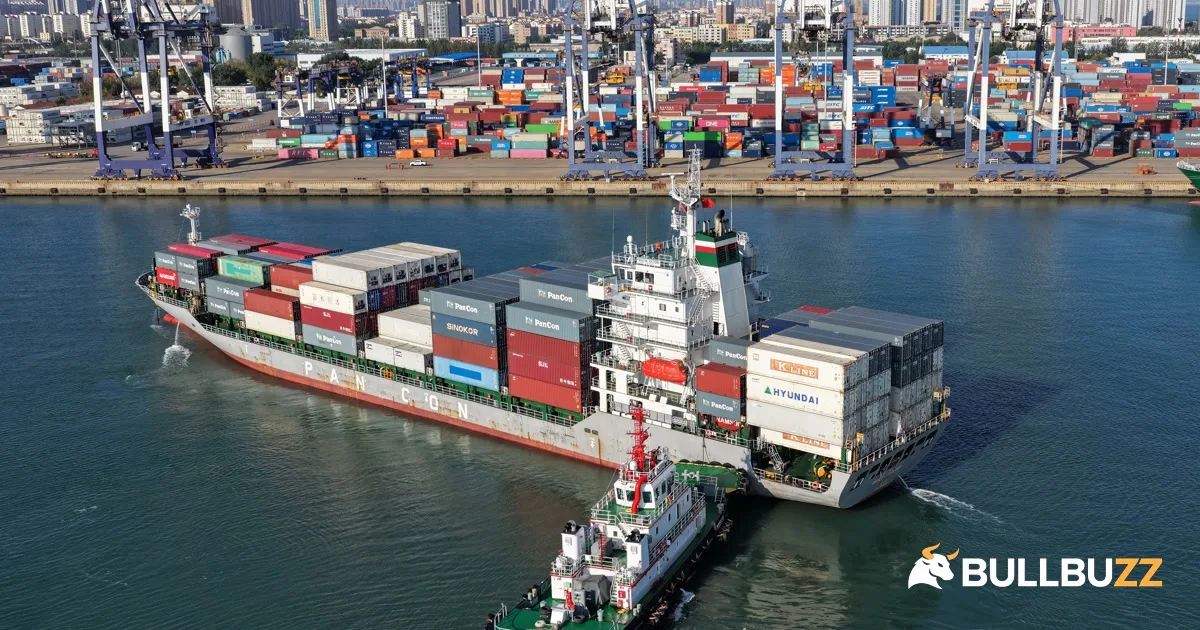
Foreign trade supplied much of the momentum. Official data showed goods exports rose 16.4% in the first nine months, while imports increased 22.3%. Mechanical and electrical products accounted for 64.3% of exports and grew 23.7%.
Manufacturing also remained firm. Value added at large industrial companies increased 5.3%, while equipment manufacturing rose 10.2% and high-tech manufacturing expanded 14.3%.
Production of 3D-printing equipment jumped 62.5%, lithium-ion batteries increased 39.5% and industrial robot output grew 29.1%. Those numbers support the view that advanced manufacturing is carrying more of China's expansion even as household spending stays subdued.
The technology cycle matters across Asia. BullBuzz's report on TSMC's 68.7% profit surge showed how semiconductor investment continues to support regional growth, while the recent KOSPI chip-stock rout exposed how quickly sentiment can reverse when financing concerns return.
Property Investment Remains the Main Drag
The stronger GDP reading did not remove China's domestic weaknesses. Fixed-asset investment fell 7.2% in the first nine months, while property development investment dropped 20.6%. Sales of newly built commercial property by floor area declined 13.2%.
Consumer demand also remained soft. Retail sales of consumer goods rose 1.1% in the first nine months, far below the growth rates in exports and high-tech production. September's 1.1% monthly reading beat forecasts but still pointed to limited household momentum.
The Associated Press reported that the property slump has weakened household wealth and encouraged saving. Economists cited by AP said strong trade is masking wider differences between industries, regions and households.
Why China's GDP Rebound Matters for Malaysia
China's growth mix has direct consequences for Asian exporters. Stronger factory production and trade can support demand for electronics, energy, logistics and industrial inputs, while weak Chinese consumption limits the benefit for companies selling directly to households.
For Malaysia, the balance between electronics demand and consumer softness is especially relevant. BullBuzz's Malaysia Q3 growth report showed manufacturing expanding 7.5%, supported by electrical and electronics activity. A resilient Chinese industrial cycle can reinforce that demand, although a property-led slowdown would pressure commodity and construction-linked trade.
The latest data may also reduce pressure for immediate broad stimulus. Reuters' economist survey found that growth is on target, but weak domestic demand, deflation pressure and the property downturn still leave risks tilted lower.
What Markets Should Watch Next
The first test is whether September's retail improvement continues through the fourth quarter. A stronger consumer recovery would make growth less dependent on exports and industrial investment.
Markets should also track property sales, fixed-asset investment and any targeted support from Beijing. Another fall in real-estate activity could pull against gains in high-tech manufacturing.
For regional markets, the yuan's response and new Chinese trade data will show whether investors treat the GDP beat as a durable rebound or a temporary lift from exports. The headline is stronger. The composition still leaves Beijing with work to do.